The last three calendar months have seen a repeat of a familiar pattern in the market. Some questions arise on AI spending, the market drops and the portfolio rises. Then within a few days an exciting piece of AI news emerges, the moves reverse and normal service is resumed. It is not just us who have noticed this. Recently the unusual structure of the equity market has been highlighted by, amongst others, Goldman Sachs, who note that a record number of stocks in the S&P 500 index are exhibiting something known as ‘negative beta’i. This is where a stock price goes down when the broader index goes up, or vice versa. We have been talking about this for some time in different way with the portfolio’s beta having declined significantly over the last couple of years, so the recent observation by market commentators absolutely rings true with our lived experience. The obvious cause is the warping of the market by the sheer size of the trade around AI.
There has definitely been a shift in market mood though. Part of this shift has meant some of the portfolio’s holdings in digital service companies deemed to be on the wrong side of the AI debate have recovered, notably Microsoft, SAP and Accenture. However, valuation opportunities continue to present themselves. Some of these are in interesting new areas for the portfolio, such as GTT in liquefied natural gas transportation design, and Honeywell International in industrial process control and building automation. Others are familiar ground. We have re-bought global eyewear market leader EssilorLuxottica, building a small position at a valuation under half of where it peaked in 2025. The stock had been bid up on excitement around its smart glasses tie-up with Meta, which we thought had got ahead of itself, so we sold the position. Now market excitement has turned to scepticism, and the ‘Succession’-like shenanigans with the Del Vecchio heirs who own a chunk of the business is also weighing on the stock. We think the family dynamic is largely a sideshow, and the valuation means we can pick up the enviable frames and lenses business at a discount and get any upside from smart glasses into the bargain.
The broad point is that there is plenty of value to be had in this market across many names, which has led us to hold a record 48 companies in the portfolio. The valuation of an individual company may be driven by idiosyncratic matters as with EssilorLuxottica, thematic factors as with digital service businesses, or macro concerns as arguably applies to consumer goods companies. This is all likely augmented by the negative beta phenomenon. Whatever the reason, the portfolio’s 16x forward price/earnings multipleii and free cash flow yieldiii of over 6%iv are very cheap compared to our expectations for these excellent businesses.
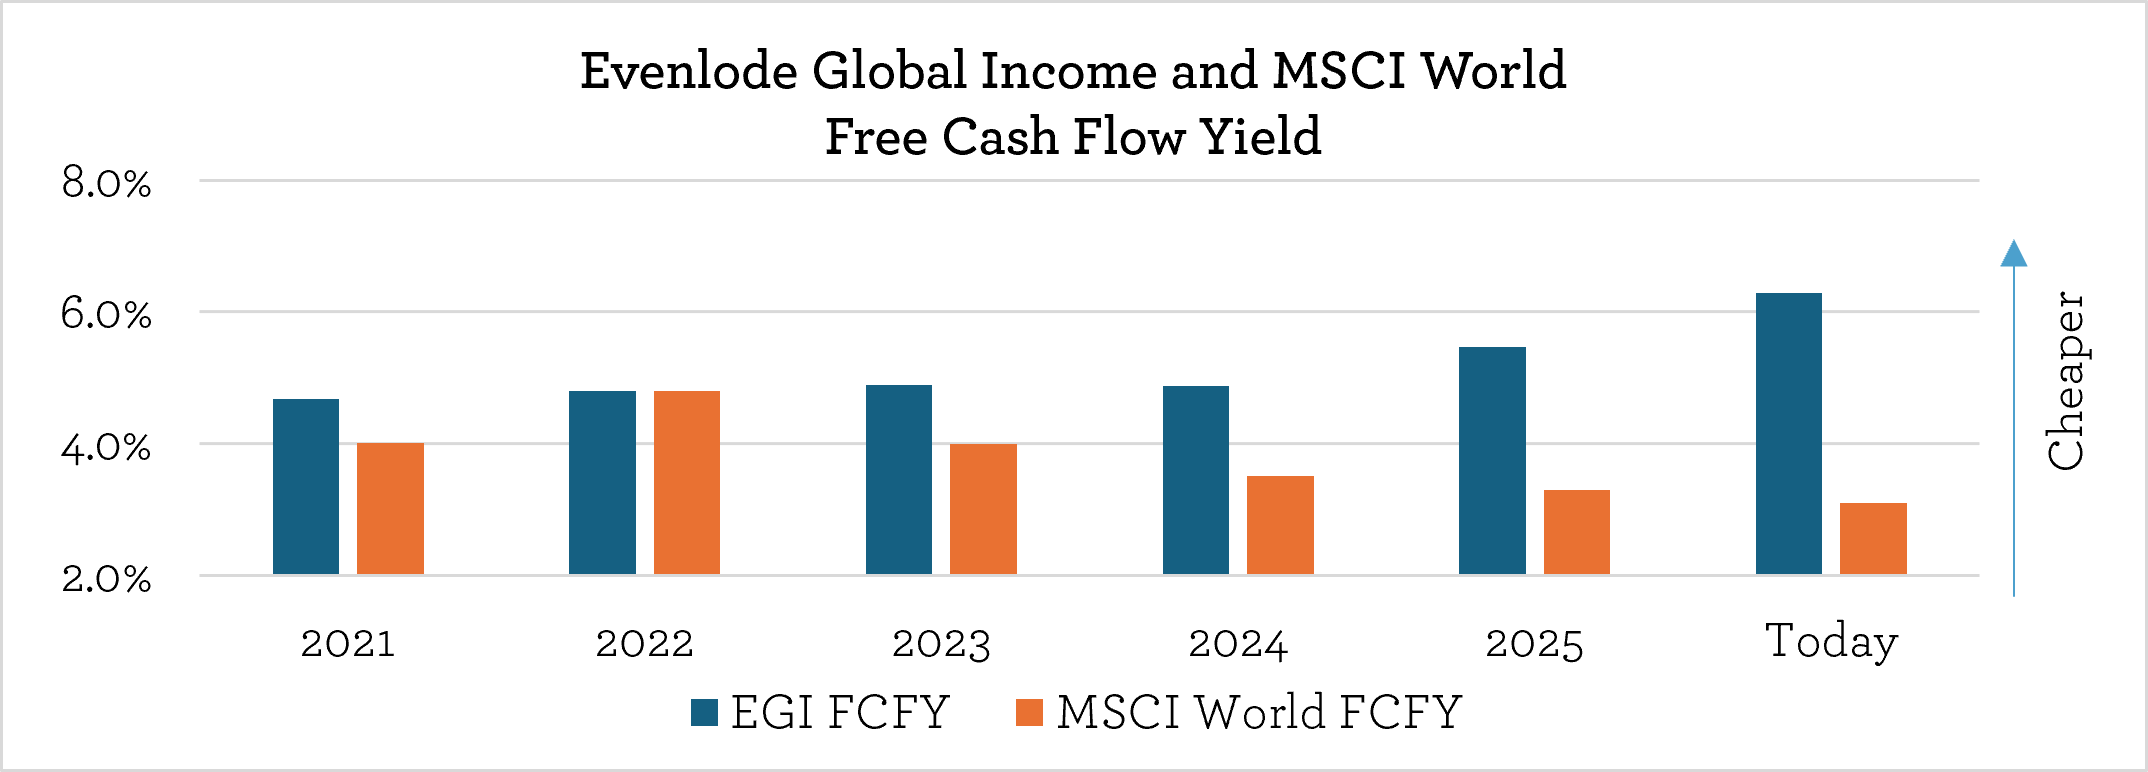
The current valuation environment in our investable universe of quality companies is reminiscent of the post-Great Financial Crisis period, an amazing statement given the bull market that has driven global indices to record highs. That quality businesses rarely get fully valued is in fact one of the attractive features of the investing style over the long term, but the discrepancy to the market is now pretty extreme.
The generation of cash from capital efficient businesses that compounds over time is not sexy or spectacular, and thanks to the mathematics of the economics does not necessitate high growth in revenues. Thus investors rarely put full value on those characteristics, generally preferring high growth rates, particularly in times of rising markets. In our estimation, our version of quality in general got somewhere close to being fairly valued in the early 2020s (and we communicated as such at the time), but the snap back over the last few years has led to a yawning valuation opportunity.
We should note that some areas of the portfolio, mainly consumer goods companies, did see their earnings growth rates moderate after the covid pandemic. All the same, we think that the negative sentiment indicated by current valuations is overdone and no heroic assumptions are required for the portfolio’s valuation to be more than justified from here. We are not sure the same can be said elsewhere.
For the portfolio, combining attractive operational and financial characteristics with low valuations creates a margin of safety, but also future value creation potential. We’re not saying that the portfolio can’t get cheaper, anything is possible. But if the valuation headwind abates, as it has somewhat in recent months, then the fundamental cash returns to shareholders will make themselves known in a positive way. That we have been able to broaden the portfolio to 48 companies adds diversification of idiosyncratic risks.
It is difficult to predict when the quality style headwind and/or the negative beta phenomenon will abate. Absent a highly unlikely permanent change to market behaviour compared to history, we think this is one of those occasional times when Mr Market is weirdly willing to sell great assets at a steep discount.
Ben Peters
25 September 2026
Evenlode has developed a Glossary to assist investors to better understand commonly used terms.
Market data is sourced from S&P Capital IQ, Financial Express Analytics and Bloomberg unless otherwise stated.
This document is not intended as a recommendation to invest in any particular asset class, security, or strategy. The information provided is for information purposes only and should not be relied upon as a recommendation to buy or sell securities. Prospective investors should seek independent financial advice.
This document has been produced by Evenlode Investment Management Limited (‘Evenlode’). Every effort is taken to ensure the accuracy of the data used in this document, but no warranties are given.
Investment commentary represents the opinions of the Evenlode team at the time of writing and does not constitute investment advice. Where opinions are expressed, they are based on current market conditions, may differ from those of other investment professionals and are subject to change without notice. Any forecasts provided are subject to change and are not guaranteed.
IFSL Evenlode Global Income is a sub-fund of the IFSL Evenlode Investment Funds ICVC. Full details of the Evenlode Funds, including risk warnings, are published in the IFSL Evenlode Investment Funds Prospectus and the IFSL Evenlode Investment Funds Key Investor Information Documents (KIIDs) which are available on request and at www.evenlodeinvestment.com.
The IFSL Evenlode Investment Funds are subject to normal stock market fluctuations and other risks inherent in such investments. The value of your investment and the income derived from it can go down as well as up, and you may not get back the money you invested. You should therefore regard your investment as long term. As a focused portfolio of between 30 and 50 investments, IFSL Evenlode Global Income may carry more risk than a fund spread over a larger number of stocks. The funds have the ability to invest in derivatives for the purposes of efficient portfolio management (techniques used by investment managers to manage a portfolio in a way that aims to improve returns, reduce risk, or manage costs, without significantly changing the overall investment strategy or risk profile), which may restrict gains in a rising market. Investments in overseas equities may be affected by changes in exchange rates, which could cause the value of your investment to increase or diminish.
Past financial performance is not a reliable indicator of future results. Fund performance figures are shown inclusive of any reinvested income and net of ongoing charges and portfolio transaction costs unless otherwise stated. The figures do not reflect any entry charge paid by individual investors. Tax treatment depends on individual circumstances and may change in the future.
Evenlode believes that delivering real, durable returns over the long term can be best achieved by integrating environmental, social and governance (ESG) factors into the risk management framework as this ensures that all long-term risks are monitored and managed on an ongoing basis. In addition to reviewing ESG factors when making investment decisions, Evenlode engages with portfolio companies on a range of ESG issues (for example greenhouse gas emission reduction). However, please note that the fund does not have a sustainability objective.
This document is neither directed to, nor intended for distribution or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation. The sale of shares of the fund may be restricted in certain jurisdictions. In particular shares may not be offered or sold, directly or indirectly in the United States or to U.S. Persons, as is more fully described in the Fund's Prospectus.
The MSCI information may only be used for your internal use, may not be reproduced or redisseminated in any form and may not be used as a basis for or a component of any financial instruments or products or indices. None of the MSCI information is intended to constitute investment advice or a recommendation to make (or refrain from making) any kind of investment decision and may not be relied on as such. Historical data and analysis should not be taken as an indication or guarantee of any future performance analysis, forecast or prediction. The MSCI information is provided on an “as is” basis and the user of this information assumes the entire risk of any use made of this information. MSCI, each of its affiliates and each other person involved in or related to compiling, computing or creating any MSCI information (collectively, the “MSCI Parties”) expressly disclaims all warranties (including, without limitation, any warranties of originality, accuracy, completeness, timeliness, non-infringement, merchantability and fitness for a particular purpose) with respect to this information. Without limiting any of the foregoing, in no event shall any MSCI Party have any liability for any direct, indirect, special, incidental, punitive, consequential (including, without limitation, lost profits) or any other damages. (www.msci.com).
Evenlode is a trading brand of Evenlode Investment Management Limited. Authorised and regulated by the Financial Conduct Authority, No. 767844. Investment Fund Services Limited is authorised and regulated by the Financial Conduct Authority, No. 464193.
Spring Capital Partners Limited is an Appointed Representative of Robert Quinn Advisory LLP, which is authorised and regulated by the Financial Conduct Authority, with FRN 548030.
Footnotes
-
A simple description here from the FT with a fun 90s cultural reference thrown in: https://www.ft.com/content/193a14eb-5650-48a8-8ead-eb8184fc50f5
-
Price / Earnings multiple - A measure of a company’s current market valuation compared to its earning potential, calculated by dividing a company’s share price by its Earnings per share (EPS).
-
Free Cash Flow Yield - The Free Cash Flow Yield is the total cash generated over and above normal operating expenses and capital expenditure by a portfolio or index, divided by the market value of the companies in the portfolio or index.
-
Source: Visible Alpha, Evenlode